 Water
 Illinois
Home / IRS
 IRS service
Your group exemption must meet Rev. Proc. 2026-8 by January 22, 2027.
The IRS replaced the 1980 rules for group exemptions. A parent organization with an existing letter has until January 22, 2027 to put its chapter roster in order, and any chapter it removes must get 30 days' notice first. The changes go to the IRS on Form 15644, by fax. We prepare the filing package for a fixed price. A licensed reviewer checks every judgment call. Your officer signs and your organization faxes it.
For US nonprofit parent organizations (central organizations) that hold an IRS group exemption letter. Send your organization's name, and your group exemption number if you have it.
Group exemptions in the IRS master file
parent organizations hold an active group exemption letter.
of them show chapters under more than one 501(c) paragraph.
show no chapters at all, so they must add one or end the letter.
Form 15644 has no online filing. The IRS takes it at 833-312-5228.
Our count from the IRS Exempt Organizations Business Master File, files eo1 to eo4, downloaded October 13, 2026. Parents are central organizations (affiliation codes 6 and 8); chapters are the subordinates listed under each group number. The file can lag a group's own records.
The rule
What Rev. Proc. 2026-8 asks of a parent with an existing letter
The IRS published Rev. Proc. 2026-8 on January 20, 2026. It replaced Rev. Proc. 80-27, the rules group exemptions had run on since 1980. It applies now, but four of its requirements give existing letters a transition period that ends January 22, 2027. Before that date, each parent must do the following.
1. Have at least one chapter, or end the letter
A parent whose letter covers no chapters must add one or terminate the letter. A chapter added now must meet the full new rules from day one, including a written authorization that says you may remove it with or without cause.
s. 12.02(2)(b); s. 4.06; s. 12.03, Example 2
2. Keep only one group letter
A parent with more than one letter chooses one to keep, sends the IRS copies of all of them, and terminates the rest. You, not the IRS, tell the chapters under the letters you end how they can get recognition on their own.
s. 12.02(2)(c); s. 12.03, Example 1
3. Every chapter affiliated and under your general supervision or control
General supervision means that every year you obtain, review and keep each chapter's finances, activities and filing status, and send chapters written information on keeping their exemption. A copy of a chapter's Form 990-N does not cover the first part. Control means, for example, that you appoint a majority of its board or officers, or a written agreement gives you control. A chapter you cannot confirm must be removed.
s. 12.02(2)(d); s. 4.02(2) to (4)
4. Every chapter in your group's 501(c) paragraph
Every chapter must be described in the paragraph of section 501(c) your group application named. Chapters in any other paragraph must be removed.
s. 12.02(2)(e); s. 12.03, Example 3
Already in line? Nothing changes.
If you have at least one chapter, one letter, every chapter in the same paragraph, and supervision or control that meets s. 4.02, the revenue procedure says you are "not required to make any changes" during the transition. Your annual Form 15644 is still due 30 to 90 days before your fiscal year ends, and any chapter you add later follows the full new rules.
s. 12.03, Example 4; s. 7.01
If the roster is not in order
The IRS may terminate a group letter if, among other grounds, the parent has no chapters, fails to exercise general supervision or control over one or more chapters, or fails to send timely and complete updates. It will remove a chapter it finds in a different paragraph. After a termination or removal, the IRS does not recognize the chapter's exemption until the chapter gets recognition another way, such as its own application. A church chapter's status is not affected.
s. 8.01(1); s. 8.02(1)(a)(iv); s. 9.02 to 9.05
No extension so far: commenters asked for a three-year transition and the IRS declined, saying it would have to run two group exemption programs side by side (Notice 2026-8). As of October 14, 2026 we found no IRS notice moving the January 22, 2027 date. Rule text: Rev. Proc. 2026-8, 2026-4 I.R.B. 380 (PDF).
Dates
Counting back from January 22, 2027
For a group that has to remove at least one chapter. Adding a chapter, ending a letter or confirming the roster needs no waiting period, but still has to be filed before January 22. Do not plan to fax on the last day.
| Date | What | Basis |
|---|---|---|
| Now to Dec. 1, 2026 | Annual Form 15644 window for groups whose fiscal year ends December 31 (opened October 2) | s. 7.01 |
| Mid November 2026 | Chapter confirmations back; the reviewer signs off the roster decisions | Our process |
| Fri., Dec. 4, 2026 | Board decision made; removal notices mailed by tracked delivery and emailed | Planning margin |
| Wed., Dec. 9, 2026 | Our suggested latest arrival of every removal notice | Planning margin |
| Wed., Dec. 23, 2026 | Last day a removal notice can arrive and still allow a removal before January 22, with no margin at all | s. 8.02(2), (3), 12.02(2); our count |
| Mon., Jan. 11, 2027 | Removal fax for notices that arrived by December 9 (day 31) | s. 8.02(2) |
| Fri., Jan. 15, 2027 | Our target for the last fax, leaving a week for a failed or unclear fax | Planning margin |
| Fri., Jan. 22, 2027 | Transition period ends | s. 12.02(2)(a) |
The December 23 date assumes the day a notice arrives counts as day 0 and that a fax on January 22 counts as before the end. The IRS has not said how it counts either, which is why we plan with margin. Orders that arrive after about November 13, 2026 and need removals run on a compressed schedule.
Your annual Form 15644 window, by fiscal year end
| Fiscal year ends | Annual window (90 to 30 days before) | Fits the transition? |
|---|---|---|
| Oct. 31, 2026 | Aug. 2 to Oct. 1, 2026, now closed | Send the transition steps as an interim update |
| Nov. 30, 2026 | Sept. 1 to Oct. 31, 2026, open now | File the annual by October 31; transition steps that are not ready go as an interim update |
| Dec. 31, 2026 | Oct. 2 to Dec. 1, 2026 | File the annual by December 1 with what is ready; removals follow as an interim update in January |
| Jan. 31, 2027 | Nov. 2, 2026 to Jan. 1, 2027 | The annual can carry additions and confirmations; removals usually need an interim update |
| Feb. 28, 2027 | Nov. 30, 2026 to Jan. 29, 2027 | The annual can carry everything if faxed by January 15 |
| March 31 to Sept. 30, 2027 | Opens after January 22, 2027 | Transition steps go as an interim update before January 22; the annual follows in its window |
Rev. Proc. 2026-8 s. 7.01. The tax year on Form 15644 must match the year on your own Form 990 or 990-EZ.
Form 15644
One form, sent by fax, signed by your officer
All four transition steps are done through supplemental group ruling information (SGRI) submissions. Since July 14, 2026 the IRS takes SGRI only on Form 15644.
- Fax only, to 833-312-5228. There is no online filing. Keep the fax confirmation page for every send: it is your only proof of the date.
- Three kinds of filing. The form has boxes for an annual update, an interim update and ending the group. You may send an update at any time, not only in your annual window.
- A roster with every change. Each list of chapters added or removed gives the name, mailing address and EIN of every chapter on it.
- Your officer signs under penalties of perjury, with title and date. There is no paid-preparer block, and the form goes in under your organization's name.
- An Adobe form. The IRS fillable PDF opens in Adobe Acrobat or Reader, not most browser viewers, and the roster section grows as you enter the count of chapters.
IRS EO Update, July 14, 2026; Form 15644 (Rev. April 2026) (PDF); Rev. Proc. 2026-8 s. 7.01, 7.02(2), 12.02(2)(f).
Removing a chapter
Two notices: one before the fax, one after
Before: letter A
At least 30 days' notice
A chapter must get at least 30 days' notice before the filing that removes it, and the removal fax may not go before the 30 days run out. Removal may be with or without cause. The rule does not say how notice is delivered, so use a method that proves the date it arrived, such as certified mail with return receipt or a tracked courier, plus email, and keep the proof.
s. 8.02(2) and (3)
After: letter B
The post-removal notice
A chapter leaves the letter on the date you notify the IRS. After the fax, you must also tell the chapter it has been removed and how it can get recognition of its exemption on its own, or claim exemption without recognition where that is allowed. Until it does, the IRS does not recognize its exemption. Keep both notices with the fax confirmation in your group exemption file.
s. 8.02(2) and (3); s. 9.03, 9.05, 9.06
Which chapters to remove is your organization's decision. The rule says which chapters cannot stay: those outside your group's paragraph, and those you cannot show are affiliated and under your general supervision or control. Whether a particular chapter passes that test is a judgment for your officers, with your counsel if the case is hard. Read the date math.
What we prepare
The filing package, ready for your officer to sign
Built from your chapter list and the IRS master file. Everything is drafted for your organization to review, decide on, sign and send.
Roster check against the IRS file
Your chapter list matched line by line to the IRS master file: names, EINs and 501(c) paragraphs, plus every chapter EIN checked against the IRS automatic revocation list. Every difference listed and explained.
Form 15644, filled in from your facts
The update for any change due by January 22, and your next annual filing, with a worksheet that shows the source of every item and flags each judgment call for the reviewer.
Chapter letters
A yearly letter on keeping exemption and a confirmation form each chapter returns; a written authorization for any chapter you add; and for each chapter you remove, the 30-day notice and the post-removal notice. Your officer adapts, signs and sends them.
Supervision records
A yearly request to each chapter for its finances, activities and filing status, a tracker for the answers, and the yearly letter: the two things s. 4.02(3) names.
Timeline for your group
Your dates counted from your order, your notice and fax dates, and your annual window from your fiscal year end. If chapters must be removed, the notice letters come first.
Fax-ready packet and filing record
The signature page marked for your officer, a fax cover sheet, and a dated record of what was sent, for your group exemption file.
Public Filing Desk
We prepare the package
- Match your roster to the IRS file
- Draft Form 15644, the letters and the supervision records
- Put it all in a fax-ready packet
Licensed reviewer
An enrolled agent or exempt-organization attorney checks every package
- Signs off every judgment call before your officer sees it
- Included in every price
Your organization
Your officer signs and your organization faxes
- Decides which chapters stay
- Signs Form 15644 under penalties of perjury
- Sends the chapter notices and faxes to 833-312-5228
We never contact the IRS or a chapter for you, and we give no legal or tax advice. We do not sign, file or speak for your organization.
The licensed reviewer
A licensed reviewer checks every judgment call before your officer signs
The reviewer is an enrolled agent or an exempt-organization attorney, working as an independent professional under their own licence and insurance. The review is included in the price.
We do not name reviewers on this site. Once you order, we give you the reviewer's name and credential so you can check them yourself. The reviewer is not our employee and confirms there is no conflict with your organization or any chapter named for removal.
What the reviewer checks and initials
- The 501(c) paragraph your group letter covers, and the document it comes from
- That each chapter kept is affiliated, and under general supervision or control, on the evidence collected
- Each chapter to be removed, and the stated reason
- Each chapter to be added: written authorization, same paragraph, and the other conditions for new chapters
- How to answer the form's attestations for chapters that existed before the new rules
- Which letter to keep, if you hold more than one, or ending a letter with no chapters
- Removal timing: proof of each notice's arrival, and a fax on or after day 31
- The type of each filing, and who signs
Questions that need an attorney, such as a chapter disputing its removal or reading a control agreement, go to an attorney: the reviewer if they are one, or your own counsel.
Sample readiness sheets
Real readiness sheets, built from the IRS master file
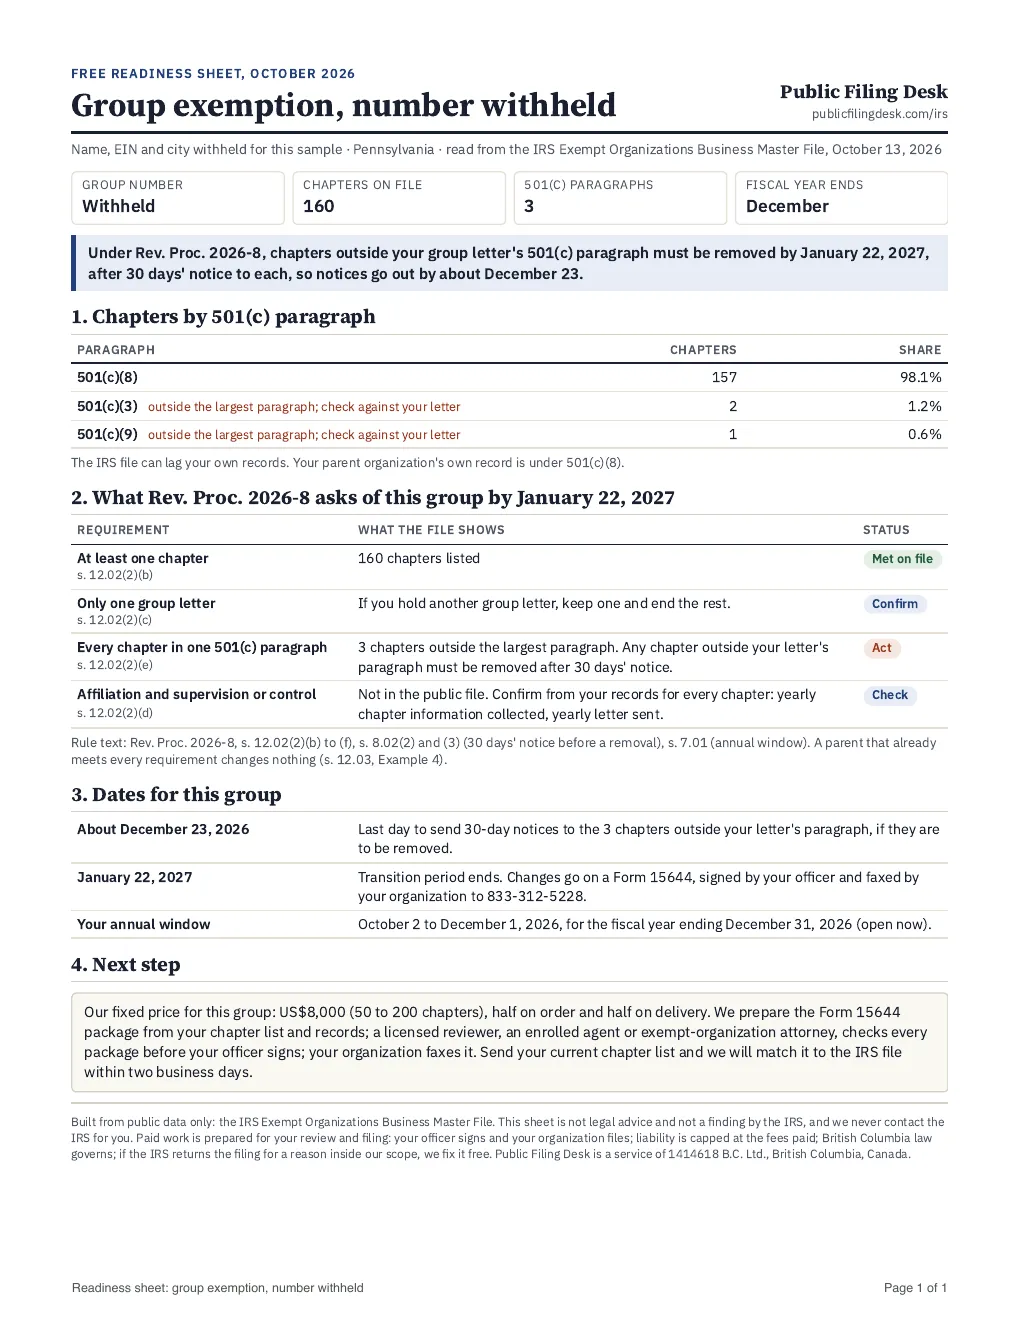
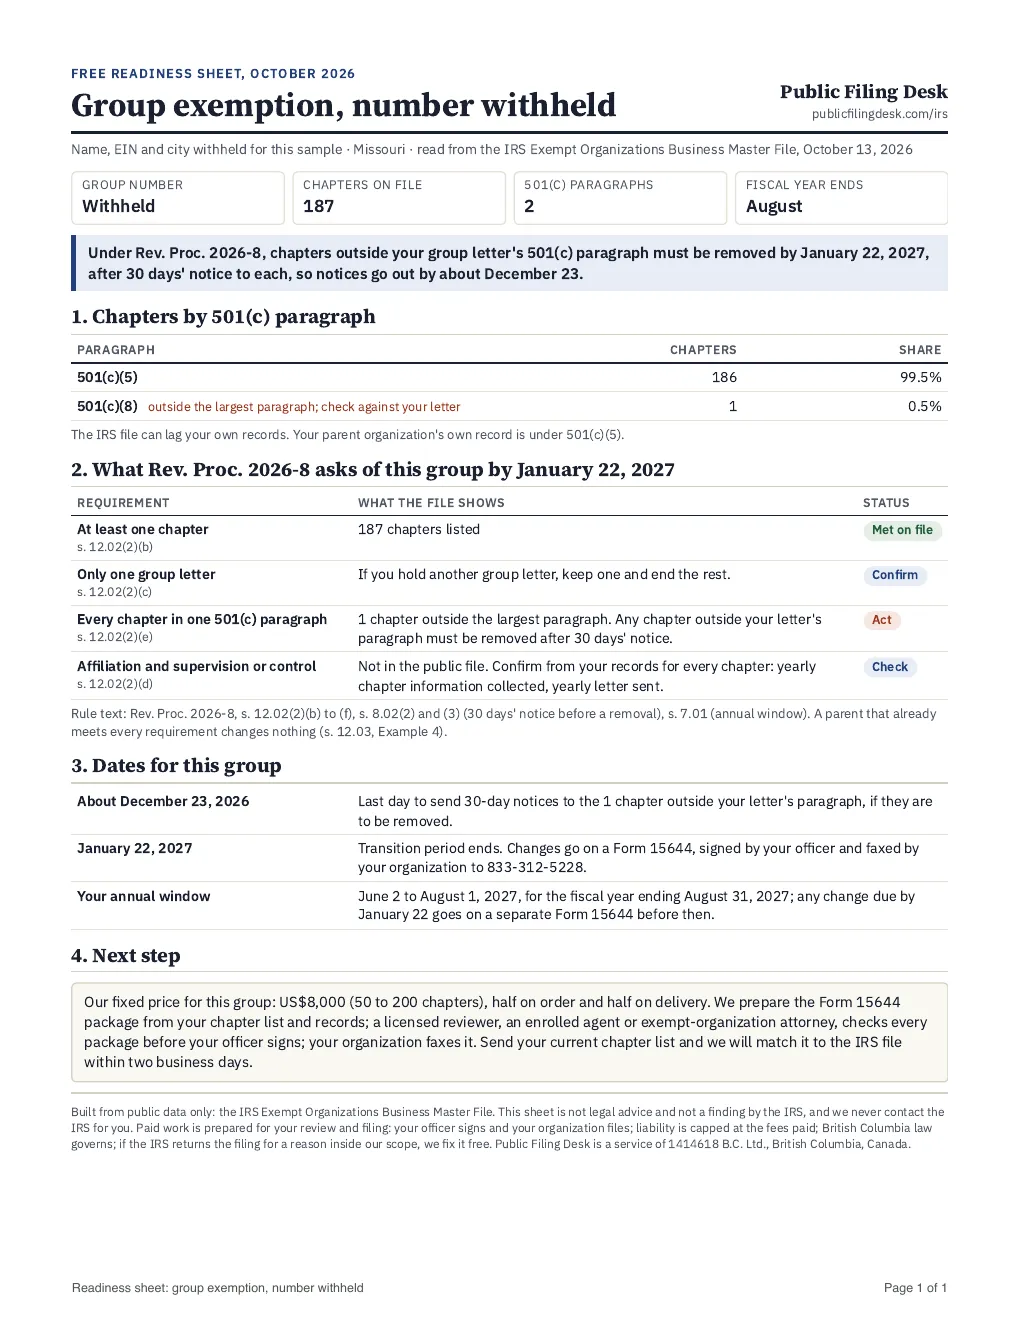
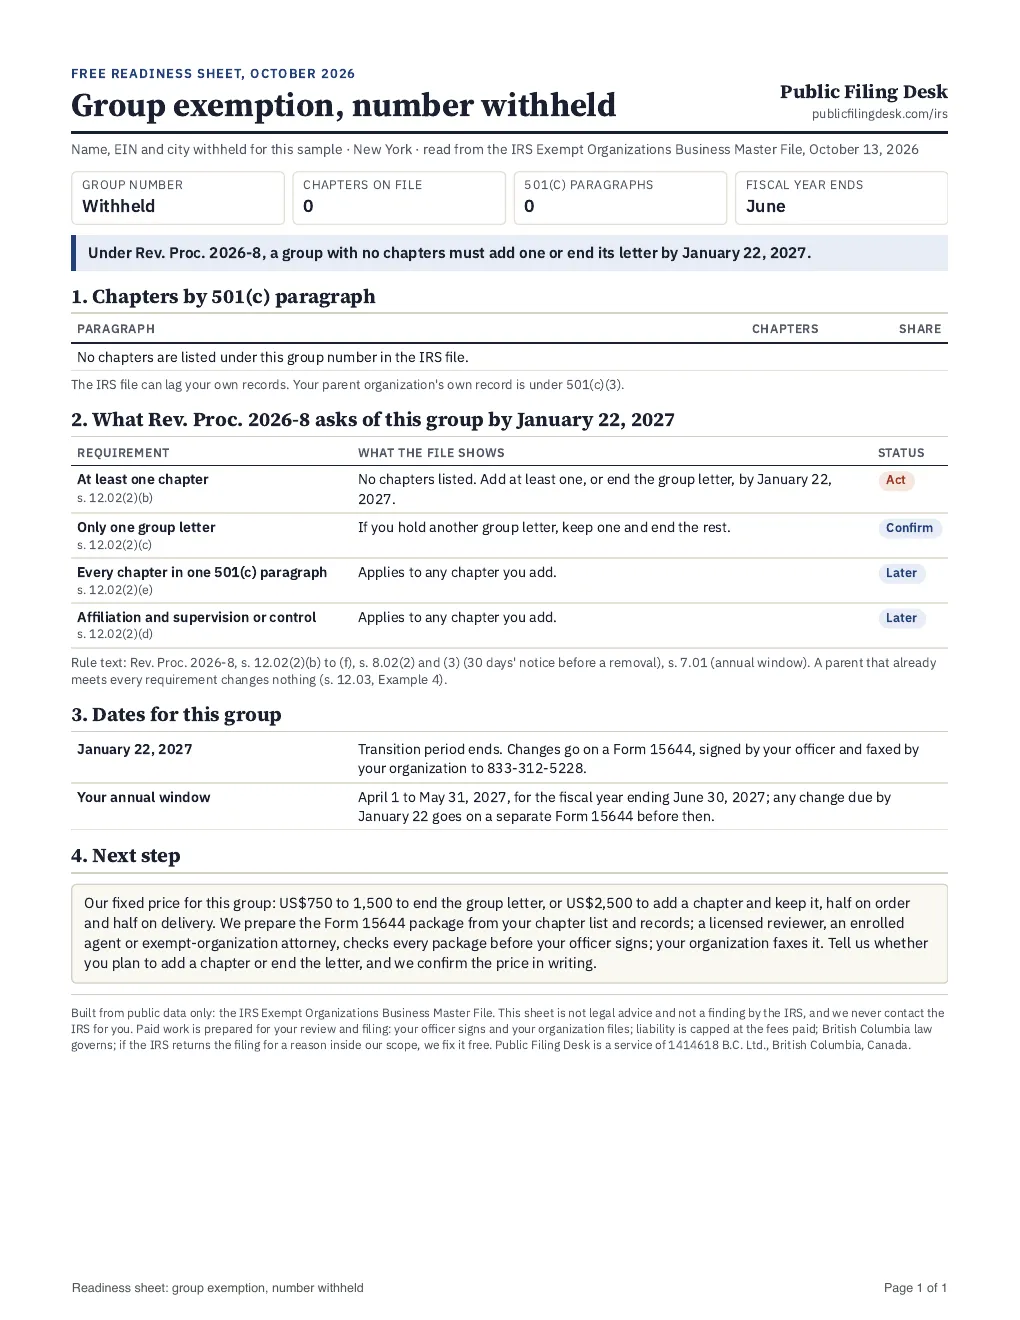
Three of the free one-page sheets we prepared from the master file downloaded October 13, 2026, with each organization's name, EIN, group number and city removed. The chapter counts, paragraphs and dates are real. Yours looks the same.
What we need from you
Your chapter list and what you already keep
Spreadsheets, PDFs and scans are all fine. Many groups have never kept supervision records in one place: we work from what exists, list what is missing, and draft what the rule names for the year ahead.
What we never ask for
IRS online account logins, chapter bank details, or members' personal information beyond each chapter's name, EIN and address.
- Your chapter list: name, EIN and mailing address for each, and the 501(c) paragraph if you know it.
- Your group exemption letter or letters and your group exemption number. Tell us if you hold more than one.
- Your most recent SGRI filing, if you have a copy.
- What you collect from chapters each year (finances, activities, filing status) and what you send them.
- Any written agreements or authorizations with chapters.
- Your fiscal year end, and whether your organization is a church or a convention of churches.
- The name and title of the officer who will sign Form 15644.
How a job runs
From your chapter list to a signed Form 15644
Free readiness sheet
Within 2 business daysEmail your organization's name. We read your record in the IRS master file and send one page: chapter count, 501(c) paragraphs, the step of the rule that applies, and your annual window.
Order and intake
Day 0We confirm the fixed price and a delivery date in writing. You pay half and send your chapter list, group letter and supervision records.
Roster and chapter letters
About day 3Roster drafted from the IRS file and the revocation list; the yearly letter and confirmation form ready for you to send to every chapter.
Reviewer sign-off and board decision
About days 14 to 21Chapter confirmations come back, the licensed reviewer signs off the judgment calls, and your board decides which chapters stay.
Notices and first fax
About days 21 to 24Your organization sends any 30-day notices and faxes the form for additions, terminations and the roster, which need no wait. The second half of the price is due on delivery of the package.
Removal fax and letter B
Day 31 after each notice arrives, before January 15Your officer faxes the removal; your organization sends each removed chapter its post-removal notice.
Every year after
30 to 90 days before your year endIf you want it, our yearly upkeep collects chapter information, prepares the yearly chapter letter and your annual Form 15644.
Pricing
One fixed price, set by the number of chapters
| Chapters | Fixed price |
|---|---|
| Under 10 | US$2,500 |
| 10 to 49 | US$4,500 |
| 50 to 200 | US$8,000 |
| More than 200 | Quoted |
The count is your chapters, not the IRS file's. If they differ, we use yours. The free readiness sheet shows which size the IRS file puts you in.
| Job | Price |
|---|---|
| Ending the group letter onlyFor a parent with no chapters, or one that chooses to end its letter: the Form 15644 termination, and notices to any chapters on getting their own recognition | US$750 to 1,500 |
| Yearly upkeep and annual SGRIYearly chapter request and tracker, yearly chapter letter, and your annual Form 15644 for your officer to sign | US$1,500 to 4,000 a year |
- Quote
- A fixed price and a delivery date, in writing, before any work starts.
- Payment
- Half when you accept the quote, half on delivery, in US dollars. Work starts when the first half is paid.
- Methods
- ACH bank transfer or check. If your rules require a card, tell us before you order and we confirm whether we can take one.
- Tax form
- We are a Canadian corporation, so US payers get IRS Form W-8BEN-E instead of a W-9.
- Ending early
- Either side may end before work starts, with a full refund of the first half.
- Not included
- Contacting or representing you before the IRS; legal opinions, such as whether a chapter is under your control; applications by removed chapters for their own recognition; group returns (Form 990) for your chapters.
- If the IRS sends it back
- If the IRS returns the filing for a reason inside our work, we fix it free.
Questions
Questions executive directors and treasurers ask
We think we already meet the rules. Do we file anything?
If you have at least one chapter, one letter, every chapter in the same 501(c) paragraph, and supervision or control that meets the rule, no roster change is needed by January 22. Your annual Form 15644 is still due each year, and our yearly upkeep covers it. A roster check is the quickest way to be sure the IRS file agrees with yours.
s. 12.03, Example 4; s. 7.01
Can we file online?
Not today. The IRS announced on July 14, 2026 that Form 15644 must be sent by fax to 833-312-5228. It covers annual filings, updates at any time, and ending a group.
Is this legal advice? Who signs?
No, it is not legal advice. We prepare the filing package from your facts. Your officer signs Form 15644, which carries a penalties of perjury declaration, and your organization faxes it. If you need an opinion on a hard case, such as whether a chapter is under your control, ask your own counsel.
Who is the licensed reviewer?
An enrolled agent or an exempt-organization attorney checks every package before your officer signs. The review is included in the price. Once you order, we give you the reviewer's name and credential so you can check them yourself. The reviewer does not contact the IRS for you, and neither do we.
Some of our chapters are missing from the IRS file. Why?
The master file lists the chapters the IRS has on record under your group number. New chapters, name changes and removals can take time to show up, and some chapters may never have been added. Matching your list to the IRS file is the first thing we do.
We have already sent some chapter notices.
Tell us the dates and how they were delivered: the 30-day clock runs from the day each one arrived. If your group already meets the rule, the readiness sheet will say so, and you may need only your annual Form 15644.
We are a church or a convention of churches.
The rule still applies to your letter, but a church central organization does not have to send the annual Form 15644, and a church chapter's exempt status is not affected by a removal or termination. Our packages are built for other groups. Ask us if you want one anyway.
s. 7.05 and 9.04
What if the IRS extends the deadline?
As of October 14, 2026 we found no IRS notice moving the January 22, 2027 date. If the IRS extends or changes the transition before we deliver, we update the package at no extra charge. If a change removes the need for the work before we start, either side can end the agreement and you get a full refund.
How long does it take?
Most of the time goes into gathering your chapter list and supervision records. We agree a delivery date in writing when you order. If chapters must be removed, we draft the notice letters first, so they can go out well before December 23.
Questions about all three services: payment, data handling, our W-8BEN-E and more
Insights
Short notes to forward to your board
What Rev. Proc. 2026-8 asks of your group by January 22, 2027
The four checks, how they are filed, what happens if you are already in line, and what happens if you are not.
Read the noteDecember 23 is the real cutoff for removing a chapter
The 30-day notice rule, counted back from January 22, and why an earlier date is safer.
Read the noteGeneral supervision, year by year
What to collect from every chapter, what to send them, and why a Form 990-N copy is not enough.
Read the noteKnow where your group stands well before December.
Send your organization's name, and your group exemption number if you have it. Within 2 business days you get a one-page readiness sheet from the IRS master file: chapter count, 501(c) paragraphs, the step of the rule that applies and your annual window. Free, no obligation.
Already have our email? Reply with your chapter list and we match it to the IRS file.